Philip Borden is CEO of shared-lab space provider Labshares and former life sciences VC and PE investor at Frazier Healthcare and Riverside Partners.
You’ve argued that biotech has a “Cathedral Problem.” What is the Cathedral Problem?
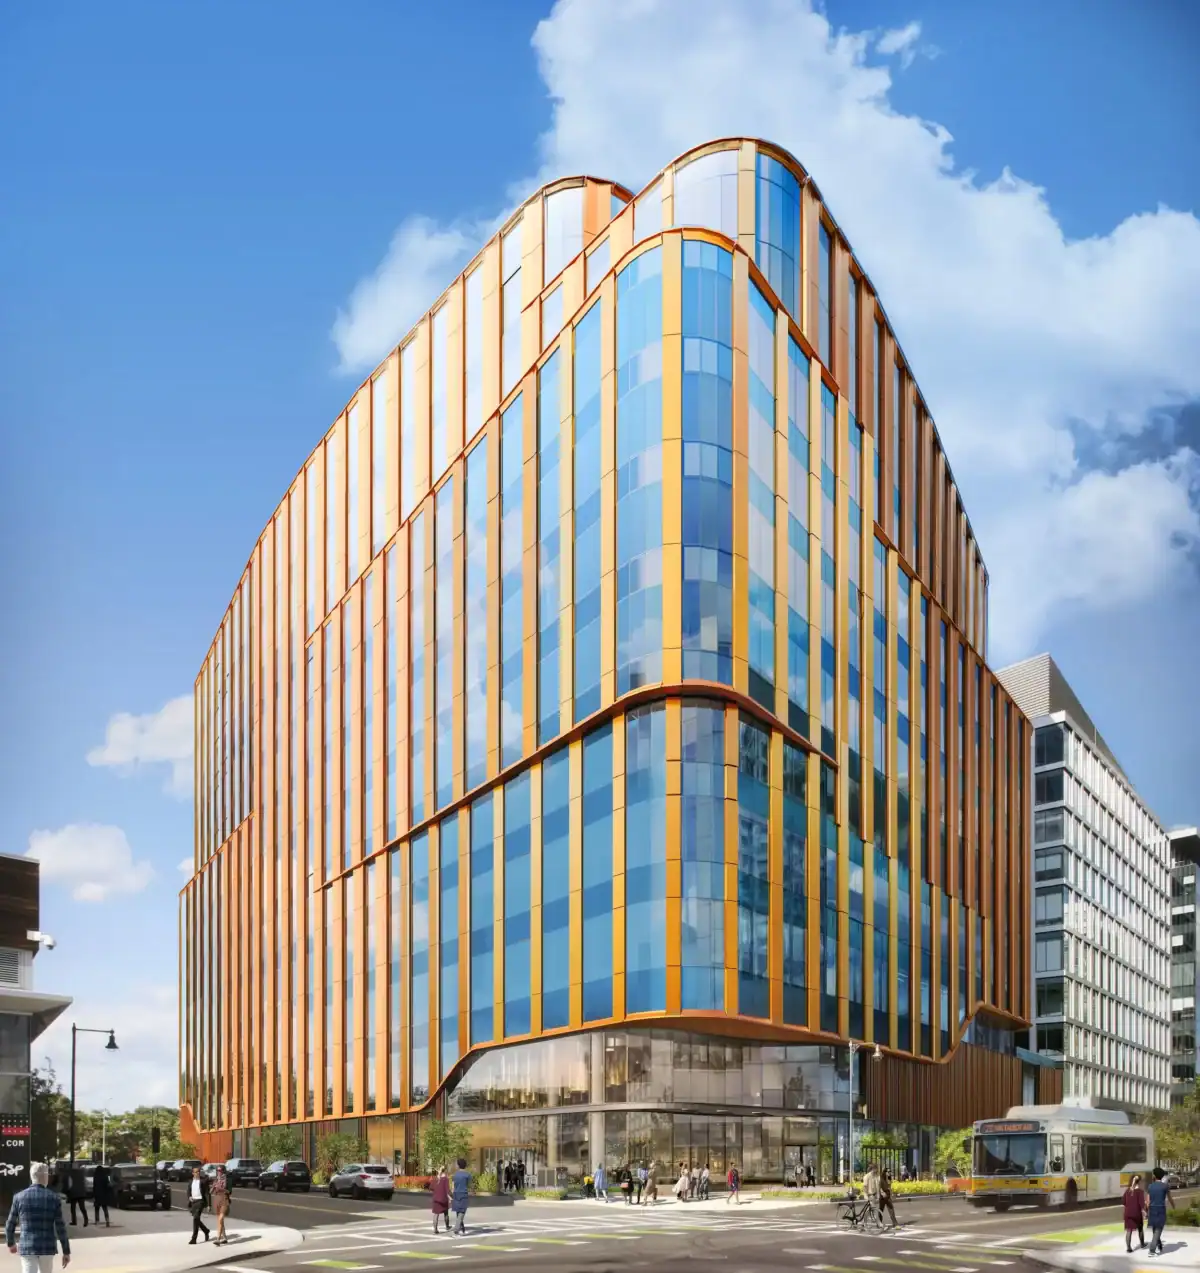
“Cathedrals” are the enormous glass-and-steel lab buildings conceived and built across Greater Boston during the 2018-2022 biotech boom. You see them now in the Seaport, Somerville, and Brighton. During those years, exuberant developers built millions of square feet of gleaming lab space on the assumption that biotech’s extraordinary growth would continue indefinitely.
But the boom didn’t last. In 2022, biotech entered a particularly brutal downturn. Funding dried up, layoffs followed, and companies that had taken on too much lab space found themselves stuck with expensive, inflexible commitments. To survive, they had to become leaner, nimbler, and much more disciplined about their lab infrastructure.
This is the Cathedral Problem: a serious mismatch between the inflexible lab space built during the boom and the evolving needs of today’s biotechs. A Cathedral can quickly become a boat anchor. Today, many of these Cathedrals sit empty — shiny symbols of speculative excess.
Companies have gotten leaner and more virtual, so why has lab infrastructure stayed on the incubator-to-lease path?
The incubator-to-lease pathway has become deeply ingrained in biotech. Emerging biotechs often begin life at an incubator like LabCentral, which is a fantastic place to launch and grow a company. But many incubators are nonprofits whose mission requires making room for the next generation of companies, so they limit how long each biotech can stay. When a biotech raises a large Seed or Series A round, the assumed next step has been to sign a lease and build its own lab.
Yet the needs of emerging biotechs have changed dramatically. Advances in AI, greater use of outsourcing, and smaller, more efficient lab equipment mean companies can accomplish more with smaller teams and less lab space. Their time in an incubator has already proven that much of their lab infrastructure can be shared, preserving capital and flexibility.
Truthfully, status is also at play. For CEOs, VCs, and boards, signing a big lab lease can feel like a sign the company has arrived. But the goal is to build a great biotech, not a great facility.
We need to rethink the idea that “graduating” from an incubator necessarily means graduating into a traditional lease. There should be another path.
What does “graduating” into your own lab actually cost — and what are the costs and operational burdens that CEOs and boards may underestimate?
I call this the “dollars-per-square-foot fallacy.” Companies focus on rent, but it typically represents only 30-40% of the true cost of operating a lab. Beyond rent, companies need to account for utilities, taxes, and CAM fees; lab equipment and service contracts; facilities and lab operations staff; safety and regulatory compliance; maintenance; and dozens of other overhead costs. Once you add it all up, our analysis shows the true cost of operating your own lab is 2x-3x the rent itself.
But there’s another cost that’s harder to quantify: distraction. Someone has to build and operate all of that infrastructure. It takes time and attention from CEOs and management teams, and none of it directly advances the science. For an emerging biotech, that’s a real opportunity cost. Every dollar tied up in lab infrastructure is a dollar that can’t extend runway, fund another experiment, or help reach the next value-creating milestone.
Massachusetts lab vacancy is around 31% while public biotech indices have recovered sharply off their 2025 lows. What do people get wrong when they read the real estate numbers as a verdict on the industry?
The mistake is treating lab vacancy as a biotech indicator rather than a real estate indicator. A 31% vacancy rate tells us there’s too much lab space—not that biotech is unhealthy.
In fact, we’re now seeing real estate and biotech diverge dramatically. Public biotech markets have more than doubled from their 2025 lows, and there are strongly positive signals in biotech IPO and M&A activity. Parabilis just completed a $770 million IPO, the largest biotech IPO in history. And it seems like every week Eli Lilly acquires another Massachusetts biotech.
But biotechs aren’t returning to the old playbook of taking on more lab infrastructure than they need. The downturn taught them to be much more disciplined about how they deploy capital.
That’s the fundamental disconnect. Biotech can recover—and even thrive—without returning to the real estate consumption of the last boom. The Cathedrals were built on the assumption that the two would always move together. They don’t anymore.
What alternatives are emerging to the traditional incubator-to-lease pathway, and what does a more flexible infrastructure model look like in practice?
Shared labs fill the gap between incubators and traditional leases – we’re increasingly seeing companies come directly to Labshares from incubators. Unlike incubators, shared labs don’t have set graduation timelines. And unlike a traditional lease, they provide shared equipment and lab operations support, reducing many of the costs and burdens of building and operating a lab. Shorter, more flexible commitments also allow companies to add space as they need it rather than years in advance.
The important shift is that shared labs don’t have to be just a steppingstone on the way to a company’s “real” lab. Today, biotechs can scale their lab space and infrastructure while staying flexible and capital efficient. For many emerging biotechs, that means they may never need to build and operate their own facility at all.
When does shared infrastructure make the most sense—and when is a traditional lease and dedicated facility still the right choice?
Shared infrastructure isn’t just for start-ups. Our analysis shows that shared labs make sense for almost any biotech with fewer than 35 employees in the lab, and Labshares is home to companies ranging from Seed stage to post-IPO.
There is absolutely a point when a traditional lease makes sense. Larger companies, or those with highly specialized requirements—BSL-3 work or radiopharma, for example—may need custom infrastructure, specialized equipment, or greater control over their environment.
The key is that taking a traditional lease should be driven by what the company actually needs—not by an outdated assumption about what biotech growth is supposed to look like.